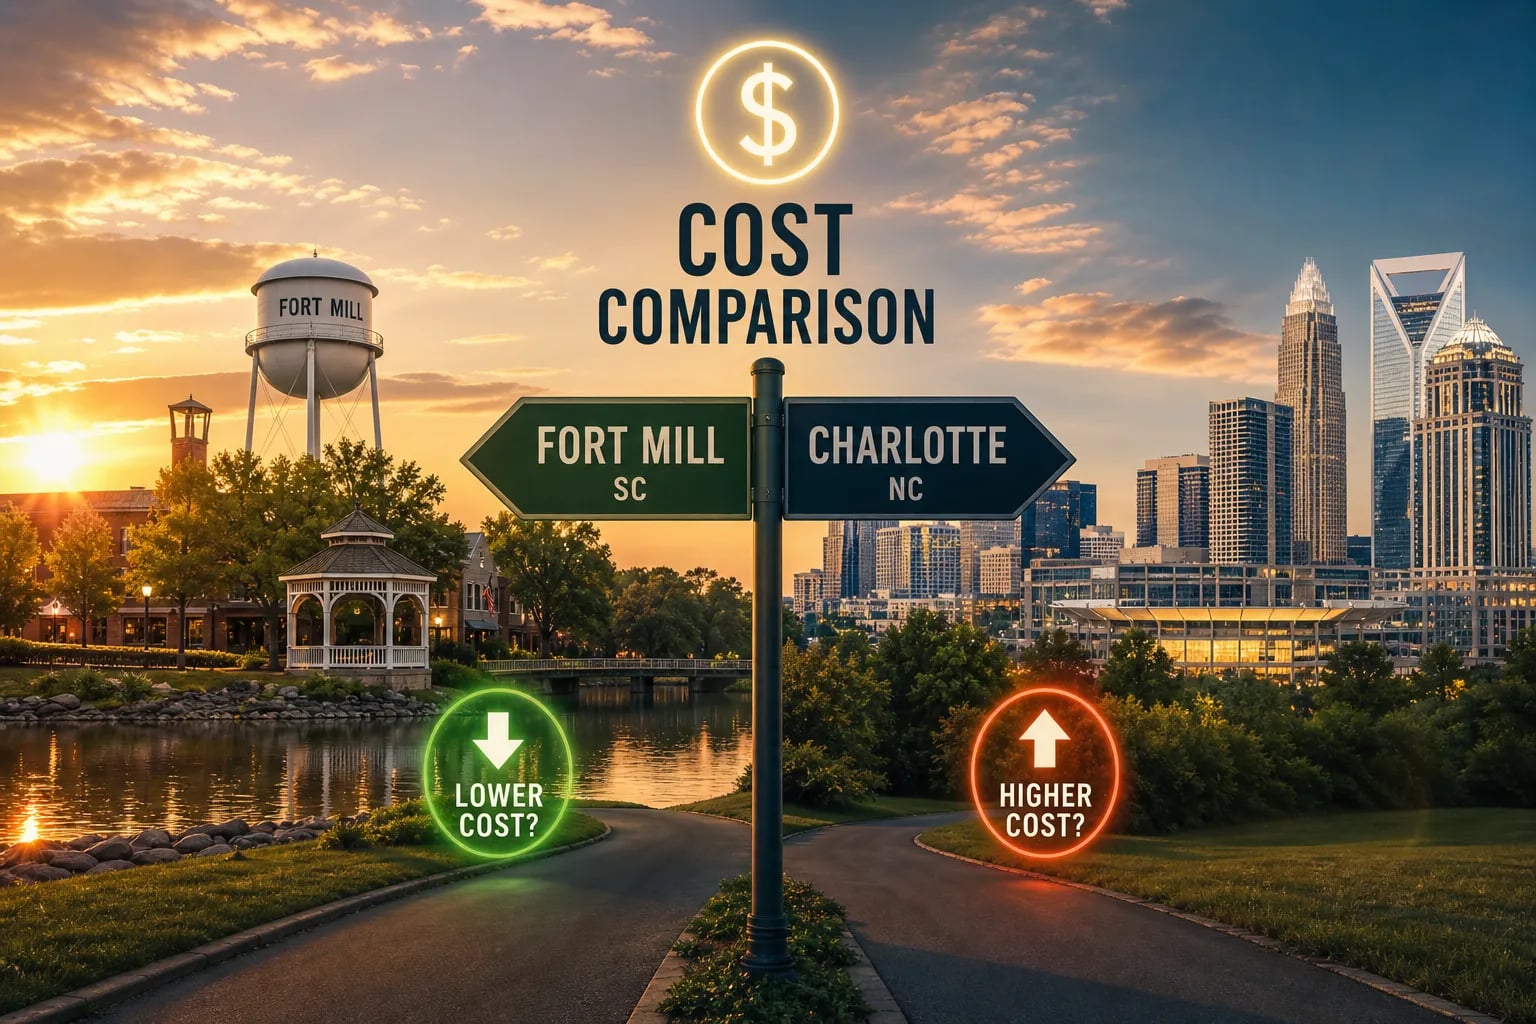
The question comes up constantly in conversations with buyers priced out of Mecklenburg County: is Fort Mill SC cheaper than Charlotte for homebuyers, or does it just look that way on a listing platform? The listing price is only one number in a much longer equation. The real cost difference lives in a stack of line items, including property taxes, state income taxes, insurance, HOA fees, vehicle taxes, and commute expenses that most buyers don’t compare until they’re already under contract.
At Carolina Realty Advisors, we run this full-cost comparison for buyers on both sides of the state line before an offer ever goes in. Broker-owner Mike Sposato holds dual licensure in North Carolina and South Carolina, which means buyers don’t get a pitch for one market over the other. They get the actual numbers for both. What those numbers show in 2026 is more nuanced than most people expect, and the answer depends heavily on your income, your commute situation, and the specific property you’re buying.
Is Fort Mill SC Cheaper Than Charlotte for Homebuyers? What Homes Actually Cost Right Now
Fort Mill’s median sale price in 2026 sits between $519,000 and $527,000 depending on the data source and measurement window. Redfin’s most recent snapshot shows a median of $526,651 with a year-over-year decline of 8.4%, which is meaningful for buyers who want negotiating leverage. That pullback doesn’t signal a distressed market. It means sellers are more realistic than they were eighteen months ago, and buyers have room they didn’t have before, a view supported by rising days-on-market and low foreclosure-rate data across York County in the same period.
Charlotte’s citywide median of approximately $430,000 looks cheaper on the surface, but that number averages some dramatically different submarkets. South End homes sell near $681,000; Ballantyne runs around $653,000. (These figures are ZIP-code-level proxies rather than precise neighborhood-wide medians, but they illustrate the spread.) Fort Mill competes directly with Charlotte’s suburban corridors at similar purchase prices, and at that price point it generally delivers newer construction and more square footage, an observation consistent with the newer build years and larger lot sizes that characterize York County’s master-planned communities relative to comparable Charlotte suburban price points. The listing-price gap narrows fast when you’re shopping the same tier of finished product in comparable suburban locations.
Property Taxes: The Clearest Financial Difference Between the Two Markets
This is where Fort Mill’s advantage becomes concrete and calculable. York County’s effective property tax rate runs approximately 0.84%, producing a median annual bill around $2,809 on the county’s median assessed value. Mecklenburg County’s combined rate, county plus city of Charlotte, works out to a higher effective burden on owner-occupied homes, with annual bills typically landing between $4,000 and $5,250 on a $500,000 to $525,000 home. Actual bills vary by municipality and special taxing districts, so confirm the specific parcel’s tax record before budgeting.
Run the comparison at a single benchmark to see the real number. On a $500,000 home, Fort Mill buyers typically save roughly $1,200 to $2,400 per year in property taxes compared to a similar home inside Charlotte’s city limits, based on the rate differential between York County’s ~0.84% effective rate and Mecklenburg County’s higher combined rate applied to the same assessed value. Translated to a monthly payment, that’s $100 to $200 per month that stays in your pocket. For most buyers in the $400,000 to $550,000 range, this is the single most persuasive number in the Fort Mill argument, and South Carolina’s assessment structure helps keep the effective rate lower than it first appears.
Monthly Carrying Costs That Don’t Show Up in the Listing Price
Insurance and Flood Risk
Homeowners insurance in Fort Mill runs roughly $1,085 to $2,430 or more per year depending on coverage level and the specific property. North Carolina homes at comparable coverage tend to run somewhat higher on state average, so this line item isn’t a dramatic Fort Mill win, but it isn’t a disadvantage either. Flood insurance is a different story: it’s priced entirely by flood zone designation, and estimates for Fort Mill ZIP codes range from a few hundred dollars annually to over $2,100. Confirm flood zone status on any specific property before assuming this number is negligible in your budget.
HOA Fees
HOA fees depend almost entirely on the specific community rather than which side of the state line you’re on. Many of Fort Mill’s newer master-planned neighborhoods carry monthly fees between $100 and $300; amenity-heavy communities like Baxter Village run toward $200 to $300 per month or higher for certain home types. Charlotte suburbs carry similar ranges. The state line doesn’t determine HOA cost, the community does, so pull the actual fee schedule before comparing total carrying costs.
Vehicle Property Tax
One recurring cost that does favor Charlotte: South Carolina taxes vehicles as personal property every year. For a two-vehicle household in York County, that adds an estimated $700 to $900 annually based on York County’s millage rate applied to typical vehicle values. North Carolina doesn’t charge the equivalent annual vehicle property tax. That’s roughly $60 to $75 per month that Fort Mill buyers pay and Charlotte buyers don’t, and it belongs in the monthly cost model, not in the footnotes. To estimate your specific bill, contact the York County Auditor’s office with your vehicle make, model, and year.
State Income Tax: Where Fort Mill’s Advantage Can Reverse Itself
South Carolina uses a graduated income tax structure in 2026: 1.99% on taxable income up to $30,000, then a formula-based marginal rate on income above that threshold, the SC Department of Revenue publishes the full rate schedule and applicable worksheet for the current tax year. North Carolina uses a flat rate of 4.25%. A straight-line comparison of those two rate schedules suggests the crossover point, where SC taxes begin to exceed NC taxes on the same income, falls in the range of $75,000 to $100,000 of taxable income, though the precise figure depends on your deductions and filing status. Below that range, South Carolina residents generally pay less in state income tax. Above it, North Carolina’s flat rate tends to produce a lower annual bill.
What that means practically: a household earning $100,000 or more in taxable income will find that North Carolina’s income tax advantage partially or fully offsets Fort Mill’s property tax savings, and the net benefit deserves a side-by-side calculation at your actual income level before drawing conclusions. A household earning $50,000 to $60,000 often comes out ahead in Fort Mill because both the property tax and income tax lines move in the same favorable direction. Retirees deserve specific attention here. South Carolina exempts Social Security income from state taxation and offers a homestead relief program for qualifying seniors, which makes Fort Mill’s cost profile particularly attractive for buyers on fixed income who are downsizing or relocating from the Northeast or Midwest.
Commute Costs and How They Reshape the Monthly Math
Fort Mill residents commuting to Uptown Charlotte on I-77 should plan for 25 to 35 minutes off-peak and 40 to 60 minutes during rush hour. The CATS 82X Rock Hill Express covers the route in about 45 minutes and costs around $5 each way. For a full-year commuter making the round trip five days a week, that’s approximately $2,600 annually before any employer subsidy. Fully loaded driving costs, fuel, tolls, parking, and vehicle depreciation, typically run $3,000 to $6,000 per year for the Fort Mill-to-Charlotte round trip, based on AAA per-mile cost estimates applied to the approximate round-trip distance and annual driving days.
Here’s what a complete monthly cost stack looks like at a $500,000 purchase price: principal and interest are identical on both sides of the state line. Property tax is lower in Fort Mill by roughly $100 to $200 per month. Homeowners insurance is comparable. HOA depends entirely on the community. Vehicle tax runs $60 to $75 per month higher in Fort Mill. Commute cost adds $250 to $500 per month, calculated as roughly $5 bus fare each way times approximately 21 working days, or driving costs prorated monthly, depending on mode and how many days per week you’re making the trip. Income tax impact depends on household earnings relative to the crossover threshold. When you total the stack, the monthly advantage in Fort Mill is real for many buyers and close to neutral for others.
Which Buyer Profiles Actually Come Out Ahead in Fort Mill
Not every buyer benefits equally from Fort Mill’s cost structure. Three profiles consistently see the strongest advantage:
- Households with taxable income below the income tax crossover range, who save on both property and income taxes at the same time
- Buyers who prioritize newer construction and more square footage at a comparable purchase price to Charlotte’s suburban corridors
- Retirees who qualify for South Carolina’s homestead relief and Social Security exemption
Buyers who work remotely or commute only two or three days per week also see more favorable math, since the commute cost line shrinks significantly when you’re not making the round trip five days a week.
Higher-income professionals earning above the income tax crossover range, and buyers who place a premium on walkable Charlotte neighborhoods like South End, Myers Park, or Dilworth, often find the math flips. The property tax savings don’t offset the income tax differential, and no amount of square footage compensates for a 45-minute commute if the lifestyle you want is in the urban core. These are not hypothetical scenarios, they are the specific conversations we have with buyers at Carolina Realty Advisors before recommending which market to focus on. This is the kind of Fort Mill homebuyer guidance that only comes from running both sides of the comparison with equal rigor.
Most buyers researching this question work with an agent licensed on only one side of the border, which creates an inherent incentive to close a deal in that agent’s own market. A broker who holds dual licensure in both NC and SC can run this cost comparison without a vested interest in which side of the line you land on. Mike Sposato at Carolina Realty Advisors has built his practice on exactly this type of advisory work, with a track record spanning more than 1,500 closings across the Charlotte region. The full financial picture, taxes, insurance, HOA, commute, and income tax exposure, is what separates a true buyer’s representative from someone who sends listing links and waits.
So is Fort Mill actually cheaper than Charlotte for homebuyers? For many buyers in the $400,000 to $550,000 purchase range with moderate taxable income, the combination of lower property taxes and favorable income tax treatment adds up to roughly $1,000 to $3,000 in real annual savings when all costs are included, for example, $1,500 in property tax savings plus $500 to $1,000 in income tax savings at a $60,000 taxable income level, net of the vehicle tax offset. For higher-income buyers, or those who want Charlotte’s established neighborhoods and walkability, the math tightens considerably and sometimes flips entirely. Charlotte suburb affordability is genuinely a street-by-street and income-level question, not a state-line question.
Before you make an offer in either market, confirm these specifics on any property you’re seriously considering: the actual property tax bill on that specific parcel, flood zone status, HOA fee and covenant details, a realistic commute cost estimate based on your actual schedule, and a household income tax comparison at your real earnings level. Working with a broker who covers both markets is the most efficient way to get all five answers in one conversation rather than five separate calls. Reach out to the team at Carolina Realty Advisors to run those numbers before you’re already under contract.